Showing posts with label Protests. Show all posts

Monday, 26 May 2014

Mea Culpa

First mea culpa, this blogging on a regular basis is a lot harder than it first appears. How Leo Kolivakis at Pension Pulse can do it every day is beyond me. As it used to say on my old school report – “Must try harder”

Second mea culpa, I also got the Ukraine situation badly wrong – the worst I foresaw was what euphemistically gets called “Collateral Damage” and we are certainly beyond that now.

Despite the situation having deteriorated farther than I anticipated, it hasn’t driven the markets down any farther. The attached chart of the Gazprom GDR shows that following the initial drop on the  invasion of Crimea it has mainly ignored recent events, although volatility has picked up. 


We have hung on to our basic positions in Russia, but more recently we have been “renting” stocks to take advantage of the volatility – buying small positions on down days they selling them out when they bounce; ideally we would be doing this as part of our option overlays, but there aren’t enough listed options on the GDRs.

Few precise details have emerged about the recent gas deal signed between Russia and China, but a couple of analysts who have run their slide-rules over what little we do know have suggested that it is at best a breakeven deal for Russia. Given that Putin was very keen to show the West that he has other choices of “friends”, it would not be surprising if China were able to drive such a hard bargain; in short, Gazprom remains a continuation of State policy by other means and as such will remain very “cheap”.

Some commentators have tried to use the deal to paint President Obama in a bad light – weak, ineffective, etc – the Realpolitik is that there is very little more he could do without Europe taking a stronger stand and there certainly doesn’t appear to be much appetite for that currently. Ironically, President Reagan warned of this kind of impasse when Western Europe first started negotiating to import Russian gas back in the 80’s

Now that Sunday’s Presidential Elections have returned the pro-European Petro Poreshenko things should calm down for a while. The forced closing of poling stations in several of the pro-Russian strongholds, such as Donetsk and Lugansk, only serve to legitimize a government that will probably be just as corrupt as the last one. It doesn’t make Russian stocks a screaming buy, but they should move slowly higher as things “normalize”

In recent weeks we have observed the Brazilian market get a bounce every time Dilma’s approval ratings drops, or word leaks out that preparations for either the World Cup or the Olympics are going badly; FIFA has said publically that the preparations for the World Cup are the worst they have ever seen, whilst the IOC has apparently informally approached the UK to see how quickly they could bring back on-line the facilities used last time around.

Congress has opened an investigation into the purchase of a refinery in Pasadena TX when Dilma was the Minister for Mines and Energy and Chairperson of Petrobras. The company was forced to acquire 100% of an operation they only wanted to acquire 50% of, paying out $1.25BN instead of their expected $360M, for an asset that was possibly only worth $42M. As a long-term follower of Petrobras, none of this surprises me.

Expectations of a first round win for Dilma have faded, although she is still currently expected to win in the second round. IF the Government is forced to introduce any kind of electricity rationing because of the poor rains, the October race will be wide open. Dilma, again in her previous role as Minister for Mines and Energy, intervened in the market to ensure that returns on investment were below those required to bring in new capital, so now the country faces a shortage of back up capacity and a $20Bn subsidy bill.

I remain confident that the World Cup will be a success, in the sense that it will happen, someone will win, and that people will have fun. Should Brazil get to lift the trophy again, they will probably deem it to be the greatest series ever.

I am happy to see the election of Narendra Modi as the new Prime minister of India. To call the Gandhi clan that has been at the core of India’s mismanagement for so long “tired and corrupt” would be an understatement. India needs someone who is not permanently trying to hold the poor back, but is actively trying to give them opportunities. Modi comes with baggage that is for sure, but he deserves the benefit of the doubt at this stage.

I used the bounce in many of the Indian names in my portfolio to cut back exposure, not because I doubt Modi’s abilities, but because I recognize that he has a herculean task ahead of him. Despite all the good wishes, we won’t know if he is actually going to be successful for quite a while as the vested interests fight to maintain their privileges.

Finally, I am surprised it took the Thai military so long to intervene in the dispute between the Government and their opponents. Given how the country has become increasingly polarized whilst the economy has slowly stagnated  - the State Planning Agency recently announced that the economy has slipped back into recession – it was only a matter of time before they stepped in. 

Unfortunately the coup isn’t likely to solve much of the underlying problem as they are too closely aligned with the “Blue Shirt” opposition of the urban elite. Perhaps they would have had more credibility if they had forced Suthep’s supporters NOT to have boycotted the Februa

Sunday, 30 March 2014

So this is spring?


Spring is supposed to be the season of renewal and rebirth, from the Prague Spring to the Arab Spring, hope springs eternal. Here in Quebec we have one of the nastiest elections I have ever witnessed, and any green-shoots outside my front door were buried by today’s snowstorm.

I confess I felt a little uneasy suggesting the other day that spring had come to the Emerging Markets. It’s always so much easier to stick to consensus and let someone else tread on the landmines first. As Keynes said, it is better to fail conventionally than to succeed unconventionally…

Still, there is no better feeling than when you do get it right. 

I should also tip my hat here to Adrian Mowat at JP Morgan. He has been consistently counter-consensus on Emerging Markets this year, and I find his positive outlook very appealing.


Markets certainly took heart from the lack of escalation in Ukraine, recognizing that the annexation of Crimea is a done deal. One may not like Realpolitik, but sometimes it is the best we can do. Meanwhile, once it becomes clear that things are not going to get worse, the only sensible thing is to make the best of a bad situation.

I would, however, argue that the rally we have experienced in more than just making the best of it.

As I mentioned in previous weeks, Fed tapering hasn’t had any effect on the ability of countries to fund themselves, and they have already raised materially more than they did during the equivalent period last year.

The biggest of the “unknown unknowns” this year has been Chinese moves to increase uncertainty in trading of the Yuan. By allowing their currency to depreciate against the Dollar, and widening the trading band, the authorities have killed the carry trade – Borrowing USD and converting the proceeds into the Chinese currency to benefit from the ever-increasing currency. Because that borrowed money has to be paid back, it has pushed the dollar up and US interest rates down, countering much of the effects of tapering. The US 10 Year bond yields 2.72% currently, which certainly does NOT represent a huge hurdle for foreign borrowers.


More recently, S&P followed through with the ratings downgrade on Brazil that I discussed in one of my initial posts, and the markets did precisely nothing on the news. In fact they actually rallied. The lack of negative action may have been related to the change of outlook to stable, since everyone knew that the downgrade was inevitable.

It may also have been obscured by the news of a corruption enquiry at Petrobras concerning the purchase of an oil refinery for $1.2BN that was really only worth $40M. Although she is not directly implicated, President Rousseff was head of Petrobras at the time of the purchase, and it has dented her credibility as a technocrat. If she had the wool pulled over her eyes on this, what else has gotten passed her?

It is telling that an event that might derail Dilma’s election prospects should cause the markets to rally. It just goes to show how badly she is deemed to be running the economy.

Yet the fact that a corruption investigation is taking place is an incremental improvement, and people are starting to look for the incremental change, such as Petrobras admitting to analysts that the numbers in its revised 5 year CAPEX plans don’t add up, and they need to look at improved cost controls. They also made it clear that the Government will give them another price increase to close the import parity gap. At the turn of the year, both these pieces of news would have been taken negatively – Brazil continues to be run badly – now they are being interpreted as Brazil recognizing it is run badly and starting to do something about it.

So the focus on Brazil is switching to what happens after the elections. If Dilma stops mismanaging things but actually tries to repair the damage, what can she do without too much shoving and losing too much face?

Elsewhere, the improvements to the current account in Indonesia appear to be solid, and the expected winner of July’s Presidential Elections Joko Widodo appears ready to tackle two of Indonesia biggest structural problems, namely poor infrastructure and the huge amount of money wasted on the fuel subsidies. The first test will be parliamentary elections to be held in April, with early expectations that his party can double their seats to around 35%.

It would be overly optimistic to say that we are now living in the best of all possible worlds.

Thailand, unfortunately, appears to be bogged down in its never-ending psychodrama. The opposition Democrat Party can’t beat the Thaksin Government in the polls, so they are boycotting them and using the courts to tie the Government up in procedural issues in an attempt to discredit them in the eyes of their supporters. As far as I can tell, their policies look more like scorched earth than anything else, and I remain confused by the relative strength of the market.

Sadly the flicker of hope that was the new SICAD2 FX system in Venezuela already appears to be snuffed out, keeping the focus on the here and now.

Just to recap, Venezuela has 4 exchange rates, the official rate decreed by Chavez at 6.3/$, the secondary rate of 11 in SICAD, the new rate in SICAD2 of approximately 57/$, and the unofficial rate in the parallel market which is somewhere around 70.

The misalignments of the exchange rate is a major cause of the shortages of everything from pharmaceuticals to toilet paper; although vital medicines and food are supposed to be imported at VEB6.3, no-one is stupid enough to sell dollars at that price. SICAD was supposed to solve that problem by auctioning off $200M or so every week at a more realistic exchange rate. Unfortunately the market demanded more dollars than that, and the Government failed to deliver even the $200M. When the VEB11 rate was set it was already too strong, and the rampant inflation since then has only served to make the situation worse, hence the third tier.

SICAD2 was supposed to be unconstrained, with rates set by the market unhindered by the Government – a huge ideological shift by the highly doctrinaire administration.

The lower exchange rate would close the budget deficit but it would drive up inflation since so much is imported; a dangerous thing when people are on the streets protesting. Unsurprisingly, the Government appears to be backtracking already, and the rates in the parallel market are falling again as citizens scramble to protect their meager savings.

Meanwhile Air Canada has stopped flying to Caracas because they haven’t been paid; arrears to international airlines are believed to have reached $3.5BN or so at the old exchange rate, whilst the Government is expected to revalue those arrears to the new rate, meaning they will only ever get cents on the dollar.


Despite the blanket of snow outside, the noisy old raccoon that was jumping up and down on my roof last week tells me that spring is really here. The renewed focus on reforms and the possibilities of future Governments suggests the markets are feeling it too.

Monday, 24 February 2014

More on Latin America's protests


Following last week’s comments about protests in Venezuela, I got an email from Christian Novak chiding me for not taking my analysis farther and discussing whether the eventual collapse of the Maduro regime will have a knock on effect on other Latin American countries, such as Argentina, Bolivia, or Peru.

Guilty as charged.

President Christina Fernandez in Argentina is already on her way out. Last October’s elections did not give her the mandate she needed to change the constitution and run for a third term. Fernandez never militarized the economy the way Chavez did, whilst all her mistakes are homegrown; there are no foreign advisors, Cuban or otherwise. Neither the IMF approved reforms to the national inflation indices nor the settlement with Repsol over YPF would not be possible without her approval, stated or otherwise.

Collapsing foreign exchange reserves seem to have done an excellent job of concentrating Fernandez’s mind. Neither the IMF backed reforms to the national inflation indices nor the settlement with Repsol over YPF would not be possible without her approval, stated or otherwise, and she would only do so if she had no other choices. Argentina’s lack of a developed Energy industry to underwrite her excesses meant she was never able to push her nationalism as far as Chavez did, despite all the rhetoric and joint issuance of bonds.

Peruvians have been much harder on President Humala than Venezuelans were on Chavez. Lacking Chavez’s charisma, his popularity slumped as the economy slowed last year. Chavez was able to put many of his cronies into positions of authority where they could seek rents unopposed, whilst Humala’s attempts to do likewise were immediately met by street protests, forcing him into a humiliating climb down.

Unlike in Venezuela, Bolivia’s Evo Morales has used the commodities boom to accumulate Foreign Exchange reserves to insulate the economy from the inevitable fall in prices, so reserves/ GDP are now amongst the highest in the world. Whereas debt/ GDP is at record levels in Venezuela (when you factor in the Chinese Oil loan and the Government’s unpaid bills), it has fallen dramatically in Bolivia. Where he has nationalized an industry, Morales has ensured that they continue to invest back into the business and remain competitive.

None of these three countries are dependent on Venezuela in any form, so a change in Government in Venezuela is not going to cause them any hardship. Despite all their fraternal leftist rhetoric, what they have actually done in practice is qualitatively different to what Venezuela has done. Any future policy changes will be independent of any changes in Venezuela.

The one country where a material change in Venezuelan policy will impact them is Cuba. The presence of so many Cuban “advisors” in the country is being increasingly questioned, and is a source of tension. This video posted to Youtube shows the arrival of another planeload of Cubans at Caracas airport being told to “Get lost!”


Currently the island receives an unknown but significant amount of cheap oil. As Venezuela’s oil revenues shrink, it will be harder and harder to maintain these subsidies, and a less accommodative government in Caracas could be as disruptive to Havana as the fall of the Berlin wall.

----------------------------------------------------------------------------------
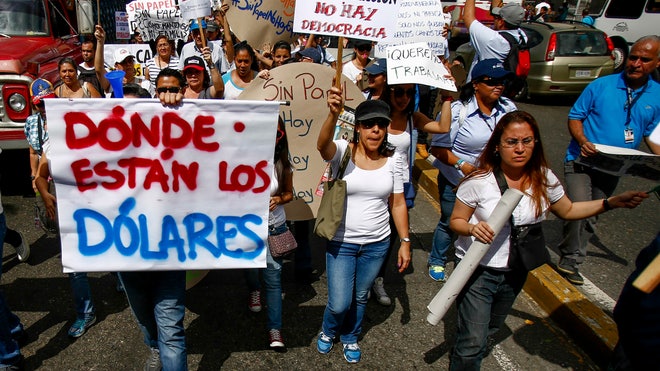
Over the weekend, some of Venezuela’s protestors tried to link what they are doing to events in the Ukraine, but the differences are probably greater that the similarities; the demonstrations in Ukraine appear to be more broadly based than in Venezuela, with a more focused leadership. The protestors in Venezuela are still seen as being predominantly Middle-Class, without clearly defined goals. Having said that, the numbers attending the anti-Maduro marches are impressive - see the picture at the top.

Finally, Colgate Palmolive announced that they would take a one-off loss of $180-200M on Venezuela’s latest devaluation. I include this little tidbit not because it refers to Venezuela, but to emphasize the increasing role Emerging Markets play in the profitability of global multinationals.


Sunday, 16 February 2014

Protests in Latin America.


This week saw three major developments in Latin America; in alphabetical order, Argentina finally produced a meaningful inflation index, Brazil officially slipped into a recession, and at least two people were killed in student protests against the Government in Venezuela.

There is a tragic inevitability about the protests in Venezuela; as the Government has radicalized and demonized any who don’t support it, they have left those who have genuine grievances nowhere to express their views in a peaceful manner. At the same time, the continued and extensive shortages of basic goods, from foodstuffs like flour to necessities like toilet paper are leaving people increasingly frustrated and disenchanted.

Toyota recently joined the long list of those cutting back on their Venezuelan operation when they announced that they would no longer be assembling vehicles in the country. The lack of dollars means that their just-in-time inventory management simply does not work, and even old-fashioned stock management is problematic because there is no way to plan stocks since there is no way of knowing when dollars will be available. In the unlikely event dollars do become available, there is no way of knowing at what exchange rate they can be bought, and at what exchange rate the finished product can be sold. Meanwhile, official waiting lists at car dealerships are apparently years long.

Unfortunately Maduro’s position is too weak for him to compromise. There are many within his own party, such as Diosdado Cabello, who are waiting for the right time to push him aside His weakness is forcing him to be “more Chavez than Chavez”. When faced with the withdrawal of firms like Toyota or the increasing shortages of basic goods, President Maduro has fallen back on increasingly bellicose rhetoric, but without the humility shown by the late President; when 20 000 tons of food rotted in Government run warehouses during the early days of the food shortages, Chavez was at least able recognized this as a Government problem and to promised to do better. As power cuts have spread into Caracas, Maduro has increasingly railed against “sabotage” by “Fascists” and “Antigovernment interests”.

The events of this week were truly tragic, and probably only the beginning. Please may I be wrong.

Brazil’s recession was equally inevitable. I believe I have nagged you enough about the failure of the current Government to enact any meaningful reforms, whilst they remain transfixed by next October’s presidential elections. There is so much that Finance Minister Mantega could have done to avoid the slowdown, but instead he fell back on the usual tried and failed policies of the past.

The ongoing protest against the World Cup are also directly linked to the weakness in the economy; many of the protestors have made it clear they want to see an improvement in Government services, from education to healthcare, whilst Inflation, although low by historic standards, is seen as a problem.

I believe, and I hope I am not being naïve in this, that the protests in Brazil are about as bad they are going to get. All sides recognized the tragic death of TV cameraman Santiago Andrade as unacceptable, whilst the Government has enlisted Pele to be their PR spokesman for why the World Cup should still take place. The fact that they are even launching such a PR campaign shows that they realize how big their problems really are. Once the games start, Brazil’s love of the beautiful game will replace any resentment over Government policies. It will then be up to the Government to build on that peace rather than squander it like they have squandered so much in recent years.

Argentina has not, as far as I am aware, suffered from the same level of street protests in recent weeks as either Brazil or Venezuela, but I think they are coming.

As I mentioned in the introduction, the Argentine Government has stopped lying about inflation. They have just announced a new index that more accurately tracks price changes, and it even appears to give a higher reading than previous private estimates. The January reading was 3.7% that annualizes out at 50%. Other private estimates were in the range of 25-30%, whilst official numbers were only 10.9% for 2013. They did not, however, rework previous numbers.

The recent devaluation of the peso will cause inflation to accelerate farther just as the Government tries to bring public spending under control. This in turn is likely to lead to conflict between the Government and unions as the Government is forced to backtrack on its “Social Justice” commitments; they have run out of their own money, and their inability to tap international capital markets means they do not have access to other people’s.

There are early signs that the economy is going into recession, if it is not already there – shorter work hours, holidays being brought forwards, possible rising unemployment.

Taking these together, and Argentina’s history of protests, it is highly likely that the erosion of purchasing power and the Government’s inability to fund its programs will bring Argentines out onto the streets in a rerun of the Cacarolazos protests that followed the 2001 financial crisis.

2014 is shaping up to be a noisy year in Latin America.