Sunday, 16 February 2014

Protests in Latin America.


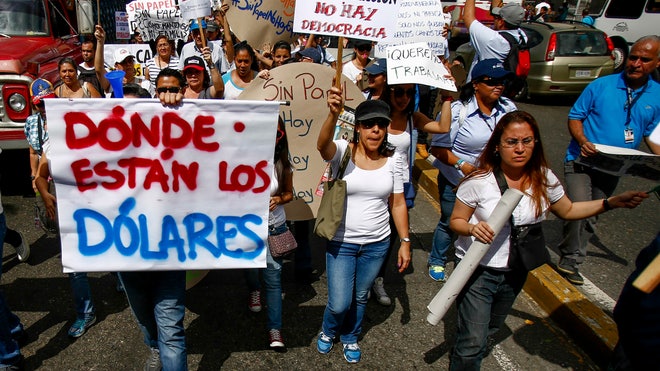
This week saw three major developments in Latin America; in alphabetical order, Argentina finally produced a meaningful inflation index, Brazil officially slipped into a recession, and at least two people were killed in student protests against the Government in Venezuela.

There is a tragic inevitability about the protests in Venezuela; as the Government has radicalized and demonized any who don’t support it, they have left those who have genuine grievances nowhere to express their views in a peaceful manner. At the same time, the continued and extensive shortages of basic goods, from foodstuffs like flour to necessities like toilet paper are leaving people increasingly frustrated and disenchanted.

Toyota recently joined the long list of those cutting back on their Venezuelan operation when they announced that they would no longer be assembling vehicles in the country. The lack of dollars means that their just-in-time inventory management simply does not work, and even old-fashioned stock management is problematic because there is no way to plan stocks since there is no way of knowing when dollars will be available. In the unlikely event dollars do become available, there is no way of knowing at what exchange rate they can be bought, and at what exchange rate the finished product can be sold. Meanwhile, official waiting lists at car dealerships are apparently years long.

Unfortunately Maduro’s position is too weak for him to compromise. There are many within his own party, such as Diosdado Cabello, who are waiting for the right time to push him aside His weakness is forcing him to be “more Chavez than Chavez”. When faced with the withdrawal of firms like Toyota or the increasing shortages of basic goods, President Maduro has fallen back on increasingly bellicose rhetoric, but without the humility shown by the late President; when 20 000 tons of food rotted in Government run warehouses during the early days of the food shortages, Chavez was at least able recognized this as a Government problem and to promised to do better. As power cuts have spread into Caracas, Maduro has increasingly railed against “sabotage” by “Fascists” and “Antigovernment interests”.

The events of this week were truly tragic, and probably only the beginning. Please may I be wrong.

Brazil’s recession was equally inevitable. I believe I have nagged you enough about the failure of the current Government to enact any meaningful reforms, whilst they remain transfixed by next October’s presidential elections. There is so much that Finance Minister Mantega could have done to avoid the slowdown, but instead he fell back on the usual tried and failed policies of the past.

The ongoing protest against the World Cup are also directly linked to the weakness in the economy; many of the protestors have made it clear they want to see an improvement in Government services, from education to healthcare, whilst Inflation, although low by historic standards, is seen as a problem.

I believe, and I hope I am not being naïve in this, that the protests in Brazil are about as bad they are going to get. All sides recognized the tragic death of TV cameraman Santiago Andrade as unacceptable, whilst the Government has enlisted Pele to be their PR spokesman for why the World Cup should still take place. The fact that they are even launching such a PR campaign shows that they realize how big their problems really are. Once the games start, Brazil’s love of the beautiful game will replace any resentment over Government policies. It will then be up to the Government to build on that peace rather than squander it like they have squandered so much in recent years.

Argentina has not, as far as I am aware, suffered from the same level of street protests in recent weeks as either Brazil or Venezuela, but I think they are coming.

As I mentioned in the introduction, the Argentine Government has stopped lying about inflation. They have just announced a new index that more accurately tracks price changes, and it even appears to give a higher reading than previous private estimates. The January reading was 3.7% that annualizes out at 50%. Other private estimates were in the range of 25-30%, whilst official numbers were only 10.9% for 2013. They did not, however, rework previous numbers.

The recent devaluation of the peso will cause inflation to accelerate farther just as the Government tries to bring public spending under control. This in turn is likely to lead to conflict between the Government and unions as the Government is forced to backtrack on its “Social Justice” commitments; they have run out of their own money, and their inability to tap international capital markets means they do not have access to other people’s.

There are early signs that the economy is going into recession, if it is not already there – shorter work hours, holidays being brought forwards, possible rising unemployment.

Taking these together, and Argentina’s history of protests, it is highly likely that the erosion of purchasing power and the Government’s inability to fund its programs will bring Argentines out onto the streets in a rerun of the Cacarolazos protests that followed the 2001 financial crisis.

2014 is shaping up to be a noisy year in Latin America.


Monday, 10 February 2014

Show me the Money!


For a great many investors, perhaps “You had me at Emerging Markets!” would have been more appropriate, but the truth for so many is that profits and market performance have too often lagged economic growth.

As I have commented in previous posts, Governments have interfered with markets to create national champions that are spectacularly inefficient, at the same time they have often turned a blind eye to corruption that has drained profits into offshore banks, or the property markets of London, Dubai, and Miami.

I was reminded of this conundrum this week whilst talking to a potential client, who asked me about China, and the somewhat bearish views of Michael Pettis. The point he was taking from Mr. Pettis’s work was that mathematically Chinese growth has to slow down more than currently expected as the economy rebalances from an investment led model to a consumption led model. I think where I disagree with Mr. Pettis is probably only a matter of timing; I think it will take a few years longer to slow growth in investment, and that raises the spectre of more malinvestment accumulating that ultimately has to be written off.

I did, however, start to think a little harder about being wrong. What would it mean if investment did slow faster or consumption grew faster than expected? I kept coming back to the 3rd Plenum last year.

Ironically, Mr. Pettis’s argument could imply a stronger case for investing in China, as it would mean that the reformers were gaining the upper hand and actually cutting the damage being done in and by the State Owned Enterprises. IF the big Chinese SOEs are forced to ration capital and raise the rates of return on investment that would have the perverse effect of raising profits as growth fell. Valuations could actually rise, given the increased transparency.  You might almost get a second wave in investment as FDI came in to take advantage of the new opportunities being opened up.

Sadly, as things stand today, this is just a pipe-dream.

China’s shadow banking system needs to be cleaned up properly first, and the authorities are still trying to hide the problems rather than deal with them.

Recently, a product sold through China’s biggest bank, ICBC, was restructured before it could go “bankrupt”.  The restructuring only involved taking a minimal haircut on interest, but left the principle intact. Given that the underlying company was entirely bankrupt, this is being interpreted as a Government bailout of some sort, even if one is not entirely sure which level of Government was involved. Needless to say, such a move is entirely at odds with the proposed reforms of the 3rd Plenum, and raised the moral hazard within the Chinese banks significantly. Plus ça Change!

Elsewhere, I am hopeful about Mexico and their attempts to pass reforms. I got some great feed back from the presentation made by Pemex at a recent conference, and the very grounded nature of Senior Management. Everyone was contrasting them to Petrobras and how much more realistic Pemex seemed.

Mexico Sovereign Debt was recently upgraded to an A- rating by Moody’s because of the reforms passed last year that should “strengthen the country’s growth prospects and fiscal fundamentals”. The country was also a winner at the recent WEF meeting in Davos, getting material commitments for new investment.

One area where reforms are taking place, and where we are seeing earnings growth commensurate with economic growth is sub-Saharan Africa. It is an area that interests me greatly and I am looking to get more involved even though I have to eat platefuls of humble pie to say that.

I don’t wish to underplay the problems with these markets; they don’t even qualify as Emerging but are firmly in the pre-Emerging/ Frontier camp. They are often so inefficient that even a slight reform can have a huge difference.

My Nigerian friends swear about the poor service of MTN and the other cellphone providers, but they will follow that up by telling you how much better even that poor service is compared to what they had before, and how it has improved their lives. At the same time MTN has been able to realize, in hard currency, substantial profits, all because the Authorities let a South African company challenge a national monopoly.

It is not just in Nigeria that change is happening. Zambia has been creating a more business friendly environment since Kenneth Kaunda was replaced in 1991. The attached article from the Economist highlights one of the better-know success stories, Zambeef.

Renaissance Capital has just started its 5th sub-Saharan investment conference in Lagos, and it looks to be a blowout. Merrill will shortly be holding their Sun City conference, which looks to be as popular as ever (it’s a great conference) but the side trips to Nigeria, Kenya etc. look like the real draw this year whereas they were not even available a few years ago.

When I was at business school, too many of my friends from these countries were desperate to get their money out. Now they are all talking about starting businesses and trying to get money in.

I would NOT recommend your average investor go out and fill their portfolio with Nigerian or Kenyan stocks, even if they were actually able to get access to them. I would, however, recommend following them in the newspapers rather than just skipping over them. If you look at say a Guinness or a Nestlé, don’t skip over any discussions of these Frontier markets, but read them carefully, because if you want to see the money, that’s where it is going to be.

....................................................................................................
 A couple of interesting videos - I'll leave it to you to decide their relative merits

Sunday, 2 February 2014

Getting Lashed by the storm

So the big sell off in Emerging Markets has finally started, looking like so much of the freak weather that has lashed North America and Europe this year.

 Last week we saw redemptions from the largest funds that matched those seen during the peak of the taper scare last year, the panic over the US debt ceiling in 2011, and even the Lehman’s crisis back in 2008. A couple more weeks of this and we will be in definite oversold/ buy Emerging Markets territory.

 We also saw some strong moves by several central banks, most notable Turkey, India, and South Africa. The Turkish move, raising the benchmark rate from 4.5% to 10% and raising the top rate from 7.75% to 12% was particularly bold. Some people even suggested that they had gone too far and that such big increases were not credible; the exit of Sterling from the ERM on Black Wednesday (16 Sept 1992) despite repeatedly raising interest rates seems to the model for such thinking.

 First of all I think this sell off is very necessary and very important. Emerging Markets are not going to be able to move forwards until this correction has happened for two important reasons. One obviously is that so many people have been expecting it that no one was going to allocate any capital until it had happened. They need to know, or at least tell their bosses, they are investing nearer the bottom than the top. The second reason is that I think it will end up showing that even the “Fragile Five” are not as fragile as bears have made out, and that this is NOT going to be a rerun of the Asia crisis of the late ‘90s.

 That does not mean that this is a storm in a teacup. I think the differences from the Asia crisis are greater than the similarities, but there are problems that need to be addressed. To misquote Anna Karenina, All well managed countries are alike; each mismanaged countries are mismanaged in their own way.

 Turkey’s rate rise will cut GDP growth significantly, and thus the skepticism about the rise’s durability. Rencap have already cut their GDP estimate down to 2% for this year, and others will follow – Merrill is still at 3.5%. Last week I described Turkey’s Finance Minister, Mehmet Simsek, as a “safe pair of hands”. I believe he has the ability to make Prime Minister Erdogan understand the gravity of the situation and that any attempt to force the Central Bank into reversing policy too soon risks losing control of the situation and making the crisis worse, jeopardizing Erdogan’s reelection hopes.

 Indonesia, probably more so than any other country, needs to cut fuel subsidies. As the FT points out, the Government in Jakarta was predicting they would eat up 11% of the national budget even before the Rupiah fell 20%. In domestic currency terms, Brent is trading at or near record levels in local currency terms across several Emerging Markets, pressuring budgets.

Tackling corruption is usually a good plan; I have been highly critical of Dilma Rousseff’s handling of the economy, but she was left a huge corruption mess my Lula, and she has tried to address it.

 In short, Governments need to follow up their stabilization plans with reforms. By and large, the countries that are suffering now have done very little to make their economies more competitive, preferring to sit back and collect the rents of the recent commodities boom and easy credit from QE. This complacency is not just a trait of Emerging Markets, as citizens of several Eurozone countries can attest, but currently the urgency is.

 To present a wish list of reforms for each and every country would be pointless, instead I will comment in the future on any that actually get implemented.

 So, what to do as we wait for those reforms? First of all, even if you believe they will happen at some point, you must remember they will probably come when politicians have their backs to the wall, meaning things could well get uglier first. If your career/ life savings depend on it, you should seriously consider waiting until you actually see something concrete happening.

 The second thing to think about is at what price you are comfortable owning something. Bear in mind, if you say today “I’d fill my boots up $20 cheaper”, what is going to make it $20 cheaper? Would you be trying to catch a falling knife, or would you be buying a cheap asset? Make sure you really know why you would buy something.

 As I mentioned last week, we had positioned some trades to benefit from the spike down, and we were able to close some shorts at really good prices on that day.

 Some of our long positions also fell back to levels we were comfortable with, but we only added incrementally so that we had money left over if they continued to fall.

 At every point you should ask yourself “What if I am wrong?” to make sure you are not being complacent.

Here is a nice video from John Authers at the FT.


Sunday, 26 January 2014

Before we were so rudely interrupted…

I didn’t intend to maintain such a long break between posts, but the cold weather here in North America caused a few unexpected problems.

Meanwhile, the world seems to have decided to go into panic mode, triggered by a fall in the Argentine Peso.

Obviously the situation really has nothing to do with Argentina and its currency mismanagement. Devaluations in Argentina are a bit like eruptions of “Old Faithful” in Yellowstone National Park; if you missed the last one; it’s never too long to wait for the next one.

In Davos this week, David Rubenstein (Carlyle Group) and Larry Fink (Blackrock) both made comments about people being too optimistic and not worried enough. I have no doubt they were including Emerging Markets in that, but EM problems have been very widely flagged since last summer, whilst the S&P has gone on to reach new highs.


From the attached Economist data table, one can see that the “Fragile Five” do indeed have week external balances. Looking at Brazil, we see a Current Account deficit of 3.7% of GDP and a Budget deficit of 2.7%, almost as bad as the UK’s numbers (3.7 and 6.7), and only slightly worse than Canada’s (3.0% and 3.0%). Most of the famous “PIIGS” have at least one measure significantly worse than the “Fragile Five”, whilst PIIGS Gross Public Debt numbers are all worse than those for the Fragile Five.

I have also attached the Economist‘s Sinodependency index, an attempt to show how dependent large US companies are on China. It would be interesting to see the concept expanded to Emerging Markets in general, and across countries other than the US; Germany’s Volkswagen is the number 1 brand in China currently. The original interactive version is available here.


I am not trying to divert attention away from the significant problems that exist in Emerging Markets; they would not be Emerging Markets if they didn’t have problems. One of the lessons, however, that should have been learned from the Global Financial Crisis was that the differences in risks between Developed Markets and Emerging are less than popularly perceived, not because Emerging risks are lower, but because Developed risks are higher, even if only because of their increased Emerging Markets exposure.

I still remain deeply skeptical of the Euro project; despite all the talk of the various PIIGS being saved, they are still massively in debt, with at least one of their major balances – usually the Budget deficit – still very ugly. The overall Euro area may be in balance but that still cleaves between an almost predatory Northern group, and the moribund Southern group; the “failure-to-launch” of the French Economy puts them firmly in the Southern group. Comments out of the UK about France being the real weak link in the Euro are probably more about British Schadenfreude for all things French, but they do serve to highlight the extent of France's problems.

The Basel III leverage requirements were recently watered down at the insistence of the German and the French Governments because it would have forced their banks to shrink their balance sheets more aggressively than is currently happening; in short, their banks still require massive regulatory forbearance because they have not been cleaned up to the extent of the US and UK banks.

The UK is expected to be the fastest growing major economies in 2014, and should be the first to raise interest rates, but that has come at the expense of a re-inflated housing bubble. It’s only a matter of time before UK TV is again dominated by shows telling everyone how easy it is to make money by flipping properties.

Shadow banking, not just in China, is going to be a major issue this year. As the FT recently reported, “Shadow banking worries extend far beyond China. Paul Tucker, a former Bank of England deputy governor, claimed on Thursday that regulators around the world were struggling to keep up with the pace of change in the “shape-shifting” non-bank sector. He warned of “faltering vigour” in official oversight of global markets.

In a paper published by the US think-tank, Brookings Institution, Mr Tucker said regulators around the world needed to display greater flexibility to cope with “endemic regulatory arbitrage and the shape-shifting dynamic of finance”, pointing to problems in both advanced and emerging market economies.’

So I have to agree with Messrs. Rubenstein and Fink, there is a lot to be worried about, but where can we look for relief?

I actually take comfort from the reduction of QE by the Fed. US house prices have clearly bottomed, and as I mentioned in a previous post, US economic growth is gaining traction. Even if that does not justify the current valuations of the S&P, a stronger US economy can only be a good thing.

Despite my fears of a UK housing bubble, their economy unquestionably has momentum, and, having used unemployment as an early indicator to raise rates, failing to follow through would undermine BoE credibility. I think even a symbolic increase of 1/8th accompanied by the message that the Bank was actively monitoring the effects of the increase on the economy, which they would be doing anyway, would send a very positive message.

The fact the Brazil’s President, Dilma Rousseff, went to Davos on a charm offensive, rather than trying to polish her socialist credentials as in previous years, suggests she at least recognizes the magnitude of her problems. A swift readjustment to imported diesel prices to compensate for the weaker exchange rate would also suggest she is prepared to act. Unfortunately, the World Cup followed by Presidential elections in October mean we are unlikely to see anything more decisive than that. IF, however, she replaces Guido Mantega as Finance Minister in her second term that would really set the markets racing.

Chinese New Year is early this year, starting January 31st. Given that it is always a confusing period for Western observers that is probably a good thing. We have already seen signs of seasonal disruption to Steel inventories, Iron ore shipments, and possibly even the PMI. Currently the prevailing attitude seems to be all news is bad news, so the sooner we can get past these distortions, the better we can understand the real situation, whatever that might be.

Turkey will get a pass. Unless PM Erdogan does something really stupid, he will ultimately enjoy the backing of the US, the EU, and the IMF, despite all the sturm and drange in the meantime. Turkey is too important an ally, and despite Erdogan’s increasingly authoritarian tendencies, the country is firmly on the democratic track. Even 10 years ago the army would have been on the streets by now. I have known Mehmet Simsek, Turkey’s Minister of Finance, for years and he is a VERY safe pair of hands.

Elsewhere, the $7 billion in investments that Enrique Peña Nieto of Mexico managed to secure at Davos shows the benefits of his reform program. I am under no illusions as to the enormity of the task ahead of him in actually implement his program, but he has already made more progress than either Presidents Fox or Calderon, and he seems to be able to forge alliances with the other parties to produce some kind of result.

Sub-Saharan Africa has seen a renaissance in recent years. The commodities boom may have triggered it but it has gained a momentum of its own as local firms, such as Dangote in Nigeria, as well multinationals such as Nestlé and South Africa’s Tiger Brands look to expand. Some of the initiatives, like Kenya’s Mpesa, are truly world class and will continue to drive growth forwards.

Currently I am working on the premise that the first half of 2014 is going to be highly volatile, with at least a major correction across all markets, but I see that correction as being highly cathartic. The kind of correction that would give Merrill's Michael Hartnett his major buy signal, so I am also putting in place my strategies for that spike down.


Sunday, 22 December 2013

Taper Tantrum

John Authers at the FT had a great video on when to Buy BRICs this week.


Given how all the research presented showed that Emerging Markets are very cheap relative to Developed Markets, it was surprising to see Andrew Pease sitting so firmly on the fence. No wonder people have such a dim view of consultants these days.

I did, however, take some comfort from him being as wrong as I was with regards to the onset of Fed Tapering; I was convinced it would not start until q1 2014.

Given the strength of US GDP revisions on Friday, in hindsight it is clear why the Fed moved when it did. Having said recently that I expect GDP estimates to get revised up in both the UK and the US in early-mid 2014, I confess I am now a little thrown that we are seeing that so soon.

Both inflation and unemployment remain below the Fed's targets, which is why the Fed has made it so clear that they do not intend to raise rates anytime soon. If, however,  GDP growth is going to surprise on the upside quite so dramatically, then QE will be withdrawn much faster than I am currently anticipating and the Fed will be forced to reconsider its rate stance. This is the biggest visible threat to my base case scenario, and with it the risk of a "melt up" in Emerging Markets.

If the risk is increasingly that of a "Melt up", the risk is not that higher interest rates depress EM valuations, but that the stronger growth in the US, UK, and Germany drags up EM earnings estimates. Merrill recently published an excellent piece outlining their thoughts for next year in Emerging Markets. They point out that bottom up earnings expectations for EMs are usually too high at the start of the year, and they generally fall as the year progresses. Expectations for 2014 are unusually low on this basis, whilst the economic outlook appears to have upside surprises.

Is this the year analysts start too pessimistic?
As the FT makes clear, we have seen massive redemptions from retail investors out of Emerging Market Bond funds ahead of Fed tapering, whilst I had previously posted a video from an RBC Portfolio Manager showing how there had been a lot of late selling by Hedge Funds who had been weak holders of EM debt. Long-term Institutional money had basically sat still. To me this says that institutions are now more firmly committed to EM markets, both debt and equity. During the Asian crisis the question was often if institutions should hold EM Assets, whilst now it is more a question how much they should hold. Andrew Pease's fence sitting was therefore more appropriate for the old way of thinking, whilst  I would advocate a bolder stance more fitting to the "modern' thinking; buy the cheap assets, but put on a hedge if you are nervous. I believe we are now at the "sell on the rumour, buy on the news" stage. The cheap parts of EM equities are now very cheap according to Merrill, with a lot of bad news built into the price; How much cheaper can they get, barring a crisis? You just need to pick the right stocks.


Wednesday, 11 December 2013

Getting a lucky break - follow up to my post on Petrobras pricing

Having talked about Petrobras's failure to establish a meaningful pricing policy,  I was fortunate enough to discuss with Sinopec (386 HK) their approach, especially in light of the liberalization of prices following the 3rd Plenum.

As I had posted earlier, the pricing adjustments announced at the 3rd Plenum were not as far reaching as the headlines suggested, as several firms had already moved to more transparent policies. In the case of Sinopec, they actually moved to an improved formula as of March 26th, including publishing the changes to their website. These changes were the 5th round of improvements to pricing since 1998.

The two key points this year were;
1) Import parity is now calculated on a 10 day moving average, down from 22 days
2) The automatic trigger was lowered from a 4% price move to RMB50/ tonne. At around 7.3 barrels/tonne and $100/ barrel, that equates to a readjustment for every 1% change in the price of oil currently.

Frankly, even if Petrobras adopted Sinopec's old formula, it would still be a huge improvement.

I also caught another break on Monday when Clément Gignac published a commentary in Canada's Globe and Mail of the end of QE and its affect on the US 10 year bond. Read the article for his methodology, but the final passage says it all,

"In a nutshell, when the Fed finally puts an end to QE, which should happen by the end of 2014, long-term rates should march up toward about 3.5 to 3.6 per cent, a rise of 75 basis points from current levels. But 10-year rates should only return to a more “normal” level of around 4.5 per cent when the Fed brings its monetary policy back to neutral, which would be in line with a Fed funds rate of about 2.5 per cent to 2.75 per cent."

Although he is slightly more "bearish" than I am (I see QE ending in 2015), I would still describe a rise in the 10 year yield to 3.5% as modest and accommodative. It is certainly not enough to derail long-term funding for Emerging Markets.

Sunday, 8 December 2013

Ordem E Progresso


Brazil, as always, continues to fascinate and excite. This week they took several steps forwards and several steps backwards; to be honest I am still trying to count how many in each direction.

Petrobras, the State owned Oil Company held a board meeting where they raised gasoline and diesel prices 4% and 8% respectively. This is good, as far as it goes. These changes should add $3.7Bn to EBITDA and $2.3Bn to net income according to Merrill Lynch.

Unfortunately they didn’t bring the domestic prices up to international parity, so the large amounts of fuel Brazil imports is still being sold at a discount – about an other 8% for gasoline and 15% for diesel, again according to Merrill.

Apart from the direct effect this has on Company and Government revenues, it has serious knock on effects to other industries, such as the domestic ethanol industry - Brazilian cars are able to run on any mixture of ethanol or gasoline.

Ethanol for fuel is a genuine green industry in Brazil, since it uses sugar cane rather than corn. Sugar cane requires basically no fertilizer (derived from oil) to grow, and can yield multiple harvests a year. Brazil has established itself a world leader not only in the production of ethanol, but also the technology that allows vehicles to be so flexible. Having encouraged huge amounts of private capital into the industry, the Government is now pulling the rug out from underneath them by crushing profitability. As a result, Private Investors are going to demand even bigger subsidies from the state development bank (BNDES) to invest in Brazil in future – hence the heavy participation of BNDES in the recent airport auctions.

Net-net, the Government is handicapping its own financing abilities AND discouraging investments at the margin, hindering economic growth.

The board also failed to specify how and when farther adjustments would be made, only that they hoped to do it over the next 24 months. This was a great opportunity for the Government to show that they were in control of the situation, and they blew it.

Petrobras was recently downgraded, and S&P has the country on negative watch. I would argue that these failures to take decisive action make a Sovereign downgrade inevitable, possibly as soon as the next review in early 2014. Should the Government continue to run such incoherent policy, a second downgrade after the elections cannot be ruled out.

I, however, still think that a second downgrade would be unlikely and a serious over reaction. As much as the Government’s policies are incoherent, they are in no ways a return to the idiocy of the pre-Real Plan days. Losing investment grade would be a major blow to national prestige and seriously undermine the Government’s credibility. When push comes to shove, I believe that the Government will do just enough to stop things getting out of control.

They have also made it clear that they recognize the effect their policies are having on Petrobras’s Balance Sheet, and its ability to fund its huge investment program. Out have gone the platitudes that Petrobras is fine, in has come the recognition of the speed with which debt is now rising and the rapid deterioration of debt metrics; The company is talking more seriously of Net Debt/ EBITDA below 2.5X, whilst it is currently over 3.1X and set to rise farther.

Barring a Sovereign crisis, and there are absolutely no rational reasons why Brazil should have one even under the current mismanagement, we are probably approaching the point of maximum pessimism. My guess, and I emphasize guess, is that it should occur during the first half of 2014. Once the World Cup starts, things will coincidently get better slowly, as the competition proves not to be a disaster, and any back up in US 10 year yields due to Fed Tapering proves to be muted; Current 10 year yields are 2.82, up from 1.62% a year ago. That is already quite a significant de facto tightening, so it's hard to see Janet Yellen trying to push rates up much farther.

There was an other development that got much less attention, but which could be very significant in the long run, if it is followed up; Brazil actually jailed corrupt Senators!

One of the causes of this summer’s riots was frustration with the politicians who had been found guilty of bribery and corruption but were able to keep themselves out of jail through complex legal wrangling. The cynical view on the street was that it would “all end in pizza”, a Brazilian term meaning the bad guys would get away with it again. Now it seems the Supreme Court has had enough too, and has sent the most visible and important members to prison – José Dirceu and Jose Genoino – along with several others.

This may be just a one-off sop to appease the rioters, and once they get bored it will be back to business as usual, but there is a very strong movement to increase transparency in Government that appears to be having an effect. I am under no illusion that Brazil will suddenly become as corruption free as Canada, but every journey starts with a single step.


Such is Progresso!