Sunday, 27 October 2013

Africa Rising


Charles Robertson, the Chief Economist from Renaissance Capital, has written a new book on Africa, called the Fastest Billion. He also got to do a TED Talk about Africa, which has just been released on the Internet.


Firstly, I love TED talks. They manage to get complex and nuanced subjects over with a degree of clarity I love and envy. I often find them a great cure to an addled mind.

This talk was no exception. It was simple and concise, but at the same time highly informative. For me there were three important messages he brought out extremely well.

Inevitability. He put up some excellent charts of GDP per capita showing the way countries have developed, especially since the birth of the Industrial Revolution. They looked remarkably like the charts Hans Rosling produces in GAPMINDER that I referred to in my introductory blog.

Obviously not all countries have historically started to develop at the same time. Local factors may hold them back or push them forwards, such an oppressive political regime or easily usable resources, but once the brakes are taken off and the engine is running, they become near impossible to stop.

It is this inevitability that too many investors miss. I am still shocked how many people I talk to still think about Emerging Markets as if they were some kind of flash-in-the-pan.

Education. I had never seen anything like his chart on education previously. I did not realize that levels in many African nations have reached the same as those we saw in Mexico and Turkey before those countries started to grow. To me this is crucial, because an educated population demands more from its politicians and no longer accepts “business as usual”. They are more able to move beyond mere subsistence living into something more structured.

When I was at university, nearly half my year was from sub-Saharan Africa, which partly explains my interest in Emerging Markets. Many had gone to British Public Schools prior to university, and the majority of them were returning home afterwards, so I should have been more tuned in to the rising educational standards.

When I first started investing in Latin America in the early 90’s, part of the argument was that there was a whole army of bright young graduates from the region who had been educated in the Developed Economies and were now returning home to use that education and to participate in the opening up of the economies. If it worked in Brazil and Mexico, why not Nigeria and Ghana?

Speed. Possibly the most contentious point he made was that Africa would now grow faster than other regions had previously. I cannot point to any empirical evidence to support that conjecture, but….

I think it was Jared Diamond in his book Guns, Germs, and Steel who explains how physical geography can affect the development and transmission of ideas; People who live in mountainous jungles are less likely to invent the wheel than people who live in more open areas. The cultivation of domesticated crops can spread more easily along lines of latitude than longitude because climate tends to be more constant.


That has probably been true over thousands of years of human history, but not so today. Today ideas can flash around the world at quantum speed. Changes to productivity that used to take decades, if not centuries can now happen in a few short years. We assume that countries will go through the whole development process the way we did, but forget that they can just buy the same technology that we have off the shelf.

I am almost the transition generation between what we might call low technology and high technology. As Douglas Adams put it in a Hitchhikers Guide to the galaxy, when I left school people used to think that digital watches were a pretty neat idea, my school was the only one in the country with a computer, and my A Level class was the first to be allowed hand calculators in the final exam.

When I was a graduate trainee, company meetings were dominated by discussions of the strategic importance of Information Technology. It soon dawned on me that it was actually a zero-sum game. Most people were following near identical strategies, whilst those that delayed would just buy the next upgrade in 6-12 months time.

A few years later, when I started travelling to Latin America regularly, it was almost like watching a Conquistador plague laying waste to Middle Management. Empty offices large enough to hold dozens, if not hundreds, of people now held 10, everyone else replaced by computers. Not clunky Brazilian import substitution computers, but the same as, or better than, I had under my desk in London. Running the same Excel or Word.

In the late 90’s, I travelled to Brazil with my then boss, and he asked the banks about their operation, and it soon became apparent to him that in many ways they were more advanced technologically than Canadian banks, with same day cheque clearing anywhere in the country, and seamlessly integrated internet and regular banking.

When I was in Bougainville last year, we passed a Cell tower that obviously had been pulled down. I my ignorance I assumed it was a tribal dispute, but no. We were informed that a local Chief had ordered its destruction after he discovered his daughter had “sexted” pictures of herself to her boyfriend!

When MTN started building its cellular operations in Nigeria, they did not start with the old analogue technology of my first cell phone, but with the latest GSM that they were installing in South Africa. M pesa in Kenya is regarded as the global standard for mobile money transfer.

So yes, I believe Africa will benefit from this acceleration of ideas. It seems that each wave of development has been faster than the one before, as each learns from the previous wave.

And worse case, that Africa’s growth will only be in line with other development waves, still points to a number of very exciting decades ahead.


Sunday, 20 October 2013

A growing China, a growing Asia.


The world breathed a sigh of relief this week when the US Government chose not to commit collective suicide just yet, although I suspect we will be reliving the drama as early as next January.

We also heard that Chinese GDP growth had accelerated from 7.5% to 7.8% annualized.  Given the determination of the authorities to make sure that the economy did not fall off a cliff, these numbers should hardly be a surprise. As with all numbers out of the Middle Kingdom, we should treat them with a certain degree of skepticism, but what matters most at this juncture is whether they were better or worse than 7.5%, rather than whether they were 7.8% or 7.7%.

The World Bank released its October East Asia Pacific Economic update, titled Rebuilding Policy Buffers, Reinvigorating Growth. This confirmed the rebound in investment in China, showing that FAI was responsible for more than ½ of the GDP growth in Q2.

FAI in China is like QE in the US, or ECB bond buying; to misquote Saint Augustine; we all want it to end, just not yet. So we should take comfort from the recent increase in Developed World forecasts from the IMF, and the nomination of Janet Yellen to replace Bernanke as Fed Chairman.

I have to assume that the consensus is correct, and that Yellen will be a “dove” when it comes to Fed Tapering, so that it will only happen slowly thus keeping policy more simulative for longer. The US should also enjoy further stimulus from the increased use of cheap shale gas.

Recent announcements from the Bank of England suggest they are in no hurry to raise rates before 2015, and the Japanese are forging ahead with Abenomics.   This all suggests to me that current IMF projections are too low, and they will be raising them again early next year. I doubt by much, but it is again the direction that is important.

If global growth is slowly being rebalanced, with the Developed Markets doing a better job of pulling their weight, we should see international trade accelerate. One of the most interesting graphs in the whole World Bank report was one for the Baltic Dry Index, showing a bounce to levels not seen in two years, which suggests such a pick up.

Baltic Dry index 5 years - Bloomberg


Paradoxically, one of the factors that vexed investors earlier this year should also help the EAP countries in this regard, namely the weaker currencies. Despite all the hysteria, the Asian Currencies had actually appreciated since the onset of the GFC, leading to fears of over valuation. That appreciation hasn’t been eliminated by this year’s weakness, but the currencies are clearly less overvalued than they were, improving export competitiveness.

Going one stage farther and looking at the underlying relationship between the whole QE program and Foreign Exchange appreciation within the major EAP countries, it is hard to find a significant correlation, suggesting that, barring a self-fulfilling panic, the effects of Tapering will be considerably more muted in the real economy.


China recently over took the US as the world’s largest trading nation (measured by Exports  + Imports), so it is seems axiomatic that China should be a major beneficiary of this firmer growth. At the margin, as global growth absorbs more Chinese exports, China can – and hopefully will – cut back on stimulus investment spending, just as the US should ease back on QE.

Easing back on stimulatory infrastructure spending as International trade picks up the slack is about as close to orthodox Keynesianism as it is possible to get these days, something the West has ben particularly poor at these last 50 years, so am I being overly optimistic that China will handle the withdrawal better than most Western Nations?

I think the key difference is that China knows its economy is gradually decelerating, and that the chances are they will need to make further stimulus investments during the current leadership period. They have made 7.5% the base line for growth for the next ten years, so they need to make sure that they have the ability to stimulate effectively should they feel that target is in danger of being breached. They also recognize that the economy is currently highly unbalanced and that the reckless pursuit of growth could undermine their long-term aims. As the World Bank report says, “The authorities recognize that growth has become too dependent on the continued expansion of investment and have articulated the need to internally rebalance the economy toward consumption-led growth, starting with the current five-year development plan.” This is not something I expect them to get perfectly right, merely good enough.

To be clear, I am not suggesting a dramatic pick up in growth and a return to the good old days. What I am suggesting is a marginal acceleration above the current projects, confirming the existing trend.


Monday, 14 October 2013

Tweedle dumb and Tweedle dee


The news that Argentina’s President, Christina Fernandez de Kirchner, was undergoing surgery to cure a minor brain hemorrhage got me thinking about the post-Christina era and comparing it to my expectations for the post-Chavez era in Venezuela. I don’t wish her ill, but it serves as a timely reminder that there will be a change in leadership by end 2015. Venezuela is obviously already in the post-Chavez era, but these are early days, so what comes next?

Argentina and Venezuela seem to have taken delight in taking a less-than-orthodox path to Economic management over recent years, both seem quite happy to take very populist positions, and regularly poking their detractors in the eye. There are many similarities between the two countries, but also striking differences.

Both economies suffer from major distortions that are slowly crushing them. Inflation is excessive by today’s standards, and Argentina actively fixes the official numbers to make it appear lower. Real CPI will be slightly under 30% this year in Argentina, and 50% in Venezuela. Predictions for next year are around 35% and 40% respectively.

Both countries suffer from a lack of foreign investment – Buenos Aires is still embroiled in a number of disputes over the 2001 default, whilst Caracas has actively discouraged FDI, often making foreign companies scapegoats for policy failures.

Infrastructure is failing due to lack of investment; they both suffer from increasing brown and even blackouts due to the failing generation and distribution capacity not being able to keep up with growing demand. In Venezuela, there have been several bridge collapses, most famously causing the closure of the Caracas – La Gauiria Highway that links the city to its airport.

Transparency International ranks Argentina 102nd ex 174 with a score of 35, whilst Venezuela ranks 165th with a score of 19, so we can consider them corrupt and very corrupt.

The Tax Justice Network, together with Britain’s Guardian newspaper, ranked both in the top 10 countries for accumulated Flight Capital in 2010. They estimated Venezuela had suffered a total flight of $405 Billion (120% of GDP), with Argentina close behind at  $399 Billion (130% of GDP). There do, however, appear to be significant differences in why capital leaves the two countries.

Capital flight is almost a national sport in Argentina. The Uruguayan capital of Montevideo is a day trip away, and many ordinary inhabitants of Buenos Aires maintain bank accounts there – frequently with the same bank they use back home. Whenever I have questioned people about their accounts, they always told the same story – we know the Government will steal our savings, we just don’t know when.

My impression has always been that Capital Flight is more of a rich man’s hobby in Venezuela, as the Government had less of a history of expropriation and hyperinflation. Even current wheezes like “The Scrape” appear designed to get dollars into the country rather than out.

Under Chavez, people have gotten very rich purely because of their connections to the regime, and they know that their wealth is safe only whilst they remain in favour. The use of the pejorative phrase “Boligarch” shows the similarities to those Russians who made out like bandits both under Yeltsin and Putin (Russia actually ranks #2 for Capital Flight according to the TJN). Like their Russian mentors, Boligarchs have a strong incentive to invest their dollars outside of the country as a hedge.

Argentina does not suffer from the same shortages of basic goods, especially food, the way Venezuela does. Argentina’s status as a major agricultural producer helps in this regard, especially when it comes to putting beef on the table. Venezuela is more import dependent making it vulnerable to the national shortage of dollars.

Argentina is firmly under civilian rule despite all the bluster over the Falkland Islands. Venezuela on the other hand is not only highly militarized, but even has the Cuban Military deeply embedded into its structure, most notably Intelligence; few people realize the key role Castro played in defeating the 2002 coup against Chavez.

The Venezuelan Government is highly ideological and everything is about promoting Bolivarianism and 21st Century Socialism, whilst the Kirchners both seemed more interested in power for power’s sake, and getting themselves reelected, rather than a messianic vision of what should be. “Peronism uses ideologies as though they were suits in a wardrobe, which it changes depending on the season,” said Ricardo Alfonsín, an opposition leader quoted in the FT. “In winter, of course, you wear a winter suit, and in summer a summer suit.”

There are Municipal Elections later this month in Argentina where the Peronists are expected to lose their majority. As the 2015 Presidential Elections approach, Fernandez will increasingly become a lame duck.

In Venezuela, President Nicolas Maduro is seeking the power to rule by decree whilst recently bolstering his revolutionary credentials by replacing the somewhat moderate Finance Minister Nelson Merentes with the more ideologically sound Rafael Ramirez. He faces considerable opposition from within the ranks of the PSUV, especially from Diosdado Cabello, Leader of the National Assembly. Meanwhile we have seen rallies of loyal troops supporting Maduro and the struggle. Because of his weak position, Maduro seems forced to be more Chavismo than Chavez, and is backing himself into a corner he cannot get out of; shortages are increasing, such as the near total disappearance of toilet paper, but to deal concretely with any of the problems risks he himself getting blamed for those shortages and being seen to be abandoning the revolution.

As Argentina’s oil imports soared earlier this year, Chevron announced a $1.24 Billion deal with Argentina’s YPF following changes to the regulatory regime that make it possible for foreign firms to make profits and to keep those profits abroad. Other firms have also signed smaller deals in apparent anticipation of a more business friendly atmosphere.

So the Argentine economy appears to be in better shape than Venezuela’s, and seems to be moving into the post-Christina era. Peronists have never been afraid of executing a volte-face. If her party takes a beating in the October 27th elections, Fernandez is likely to use her illness to duck out of farther politics, blaming Vice President and acting President Amadou Boudou for the defeat, with Sergio Massa being the most likely beneficiary. If he makes significant gains I think his business friendly approach should lead to opportunities in both infrastructure and the local stock market should he go on to win the 2015 Presidential Elections. Even if he does not make such gains, the overall approach is becoming less business antagonistic, and selective infrastructure investments are likely to become attractive in the next 3-5 years as the next administration seeks to correct many of the problems currently plaguing the economy.

I was more optimistic about Venezuela earlier in the year; there appeared to be signs of rapprochement between Maduro and some of the important business leaders. Since then, he seems to have lurched farther left again, and his pronouncements more hysterical. Although he has made some progress on obtaining limited funding from the likes of Rosneft and Chevron, they are not sufficient to reverse the decline.

I think the window for an easy transition in Venezuela is closing rapidly. The changes at the Ministry of Finance suggest that the corrections to the FX regime will be mishandled. Ramirez is more likely to validate the obvious overshoot that is taking place rather than address the root cause. Thus it would not surprise me if inflation continued to accelerate.

There is little hope of any material change to supply, meaning that shortages will continue to get worse. At some point, even the staunchest of Chavez supporters are going to notice the empty shelves. If he is lucky, this is the point Maduro will be replaced and forced into exile. If he is unlucky, he will get to stay in power and preside over a very traumatic transition. This is also the point street demonstrations could turn violent. This time, the old Baron Rothschild aphorism of “Buy when there is blood on the streets” probably won’t apply, and I say that having used it to great effect when Chavez first burst upon the scene.

In conclusion, I am much more confident about the transition in Argentina. I believe we are already seeing positive signs of a more business friendly environment under the next administration. In Venezuela, however, I think the more likely scenario is that it gets even worse before it gets better, and the longer the process the worse it will be.


I hope I am wrong.

Sunday, 6 October 2013

Corporate America, the Fed, and Emerging Markets


Last week I went a little off-piste, talking more about the problems of start-ups and the failure of Investment Consultants rather than Emerging Markets.  

I am back on track this week.

One of the points I tried to make in my introductory blog was that the Fed could not afford to “ Taper and be damned” when it can to the Emerging Markets, because the linkages between GEMs and Developed Market Companies were now too strong.

The risks of collateral damage from too aggressive tightening was brought home this week when Unilever posted a warning that sales growth would be below analyst’s forecasts of 4.5 - 5%, and nearer 3 - 3.5%. This comes after the company paid $3.2 BN in the summer to raise its stake in its Indian subsidiary, Hindustan Lever, from 52% to 67%. The acquisition shows how investment in Emerging Markets has been key to the company’s recent strategy. (Unilever is currently sticking with full year targets, although most analysts appear to have trimmed full year estimates) 

As the FT video makes clear, GEMs now make up over 57% of sales for Unilever


Many other consumer companies, such as SABMiller, Nestlé, and Diageo also got caught in the downdraught, as analysts fretted about their Emerging Markets exposure. These companies are major blue chips in every sense.

Although not Taper related, Colgate provides us with a good work through of the problem. It was forced to take a 1st Quarter charge of $120M on the back of Venezuela’s devaluation in April; Venezuelan sales make up about 5% of total sales for Colgate.

It is interesting to look at where Colgate’s growth was coming from during that quarter – per the WSJ

“Colgate's sales growth came primarily from higher sales volume. Prices were 1.5% higher, on average, compared with last year. Organic sales rose in each geographic region, with North America up 5.5%, Latin America up 9%, Europe and the South Pacific up 0.5% and Greater Asia and Africa up 10%.”

Page 81 of Colgate’s 2012 10 – K shows us 2012 sales breakdown by region.

Reworked as a pie chart you get the following distribution.


All these companies are solid Blue Chips; they employ hundreds of thousand of Americans, and you will find their shares at the core of any “safe” American retirement portfolio. Many of them hold significant cash balances overseas that the Government would very much like to see repatriated. I could have trawled most of the S&P 500 and got reasonably consistent results – from GE’s 10-K “Our growth is subject to global economic and political risks.
We operate in virtually every part of the world and serve customers in more than 100 countries. In 2012, approximately 52% of our revenue was attributable to
activities outside the United States. Our operations are subject to the effects of global competition and geopolitical risks.”

In short, the Fed could not afford to taper aggressively not because of the damage it would do to the Emerging Markets, but because of the damage the Emerging Markets would do to the US.


It’s a whole new world out there.

Sunday, 29 September 2013

Biting the hand that feeds


The FT last week published a story looking at a recent Saïd Business school study on Pension Fund Consultants, and their lack of value added. In fact, they seem to be value destructive according to the study.

This immediately made me think of Leo Kolivakis’s recent Pension Pulse article on Hedge funds, and how the consultants tend to push large funds over small, despite small funds getting better performance.

This is not a new phenomenon, and it is not just confined to the Pension Fund industry. Back in the 70’s and 80’s, it was well known that “No-one ever got fired for buying IBM”. I remember as a junior US analyst opening my FT one morning to see an advert by Compaq, who were setting all sorts of records at the time for revenue growth, S&P inclusion, etc. “and no-one got promoted for buying IBM either”.

There are many reasons for these trends, but I would suggest career risk is actually the biggest. As Leo put it:

“Fifth, there is a herd mentality among large investors who pretty much all invest in the same large brand name funds. Much easier to go in front of your board if some well known fund you invested in is performing terribly and say "everyone was invested in this fund, they had stellar performance in previous years and we were caught off guard by their recent dismal performance." It's all about managing career risk and those allocating to hedge funds rarely, if ever, stick their necks out to invest large amounts in smaller hedge funds because if something goes wrong, they're cooked!!!”

When I tried to set up my own funds and I had managed to get myself in front of consultants and managers here in Canada, they told me the same thing; They knew I could do the job as well as any “known” firm, but if this was the year I had bad performance, their bosses would crucify them. I could come back in 3 years, with at least $100M under management, and then we might talk.

I was told recently that one of our major Pension funds here had no Canadian managed funds in their external portfolio. Funds normally suffer from Home Market bias, the tendency to view more favourably the markets one knows best, so one would expect Canadian managed funds to be overrepresented, not under.

When I look through the list of Emerging Markets mutual funds offered to retail here, I am always shocked how few are managed here. The list of fund continues to grow, but when you drill down, they are managed outside of the country, even when sponsored by our largest banks.

Would I be pushing the bounds of credulity to suggest that there is a correlation between the lack of support for start-up firms and the outsourcing of so much of our funds under management?

Now many people will come back that there are fiduciary duties to uphold and due diligence to be performed, all of which is true. Regulations were, at least in theory, put in place to protect against some kind of problem.

And despite all those regulations and due diligence to protect us, we still have Madoff, SAC, and a host of others.

I have described a particularly Canadian situation, but the Saïd study above is for American funds. I would hazard a guess that you would see similar results if you analyzed European funds. Local differences abound, but the underlying problem remains: the playing field is tilted too steeply against new funds.

Not all is lost. I was talking to Ramy Zakher at OMERS recently who told me they had started to look at firms who had only $50M under management, but they would be looking to take a stake in the company for their funding. This is a huge step forwards.

Here in Quebec, we have, at least in theory, a scheme to support new funds, but sadly, execution so far has been less than adequate. So bad in fact that the backers of the program have started to ask why the managers are sitting on their hands, and starting to hold them accountable

What solutions would I propose?

I would recommend everyone involved, but especially the beneficiaries and trustees of schemes, to start asking what their managers and consultants are doing to recommend smaller firms. Given that these funds have better performance, don’t trustees have a fiduciary duty to be asking the question?

I would recommend regulators introduce more asymmetric regulation, with sensibly easier rules for smaller funds. When I managed long - short for High Net Worth clients, I was doing it on a managed account basis, so I had no access of any sort to the client funds, and all the trades I executed were reported directly to the clients, who were all accredited investors. Yet I had to put up the same regulatory capital as if I were a hedge fund, which ended up killing the project.

Many US States have rules to invest minimum amounts with minority owned firms. How difficult would it be to extend that to firms below say $250M AUM?

For large State funds, the press should be asking why so much is outsourced to external managers. Some administrations have a problem paying “Wall St” wages, but are happy to pay millions in fees to Wall St. There are a lot of good managers and analysts who would be very happy making a good salary at a State fund. Ontario Teachers’ Pension Plan would be a fantastic role model for them.

Consultants need to be more proactive. They need get involved at a much earlier stage and to set up platforms that are easy for anyone to promote themselves, even a dart-throwing monkey. Instead of complaining that smaller funds need to do a better job marketing themselves, they should be helping them market themselves – the whole point is that you want the smaller funds to be managing money.

I am probably wildly optimistic, but I believe that if small firms can get this kind of support, it can rapidly become a self-sustaining “ecosystem”, as successful funds grow, and unsuccessful ones die, their seed capital gets returned to the pool to seed the next generation.

Post Script.

As I was proof reading this, the FT published a follow up article on consultants here


Saturday, 21 September 2013

Slow Money Moving Slowly Forwards


I participated this week in a conference at Quebec’s Caisse de Depot, the Provincial Pension Fund Manager. Before they were recently over taken by CPPIB, they were the largest Government fund in Canada, and for 12 years I ran their Emerging Markets Equities team there.

I used the opportunity to talk to friends and former colleagues, and to get an update on what they were doing in Emerging Markets. I have to say it was reassuring to hear that so many of the strategies I had helped initiate with Ghislain Parent, the former CFO, were still progressing.

It was also interesting to hear the list of countries they were targeting for increased infrastructure investment; It was a short-list of countries that the press today insists are about to undergo major crises. They confirmed my point from last week that the duration of any crisis would be so short compared to not only the construction cycle but also the life of the project as to be irrelevant.

This is slow money moving slowly forwards.

Every year the Caisse holds a conference on sustainable investment, this year’s conference was on the subject L’EAU EN ACTION$
Implications pour les investisseurs.

From the title alone, it should be clear that this was the Caisse looking ahead years and decades rather than weeks and months; slow money moving slowly forwards.

Why do organizations like the Caisse take such a long view, and why are they not as panicked as the press by all these imminent crises?

These funds have very long-term liabilities, and their planning needs to match that. Here in Canada, our main pension funds are regularly tested to make sure they are actuarially sound for 70 years. That may seem obvious, but too many pension funds across the world are in deep trouble precisely because their sponsors failed to plan adequately; Detroit’s recent bankruptcy filing was merely the tip of an iceberg.

By planning this far ahead, the Caisse and others identify new and up coming opportunities to invest in AND threats to their existing investments. They get to invest in horseless carriages and pocket calculators rather than continuing to invest in buggy whips or slide-rules.

Growing up in rainy England, we had regular droughts through the 70’s and 80’s, as the storage of all that rain was simply inadequate. Here in Canada, we tend to think of water as a limitless resource, but even that can be over optimistic. The dormitory town I live in just out side of Montreal is looking for their second new water supply in only 5 years because the previous new water wells are already silting up.

China has about 20% of the world’s population but only 6% of the world’s usable water. Most people are aware of the air, ground, and water pollution in China even if they haven’t even been there, so it is probably uncontroversial to say even that 6% is optimistic; I have never been to that part of China, but I am told the water behind the Three Gorges Dam was basically an open sewer before the dam was even finished. China has even started blocking new production facilities because the designs do not include adequate plans for water supply or treatment.

India is in many ways worse than China, with 16% of the world’s population, yet only 4% of its water resources. Recall also that India’s population is expected to outstrip that of China in a few years.

I borrowed the chart below from the presentation by Pierre Fournier of National Bank, which shows the historic and UN Projections for increases in demand for various agricultural products – Meat, Milk Products, Cereals, and Vegetables


It illustrates nicely how increased wealth leads to increased protein consumption.

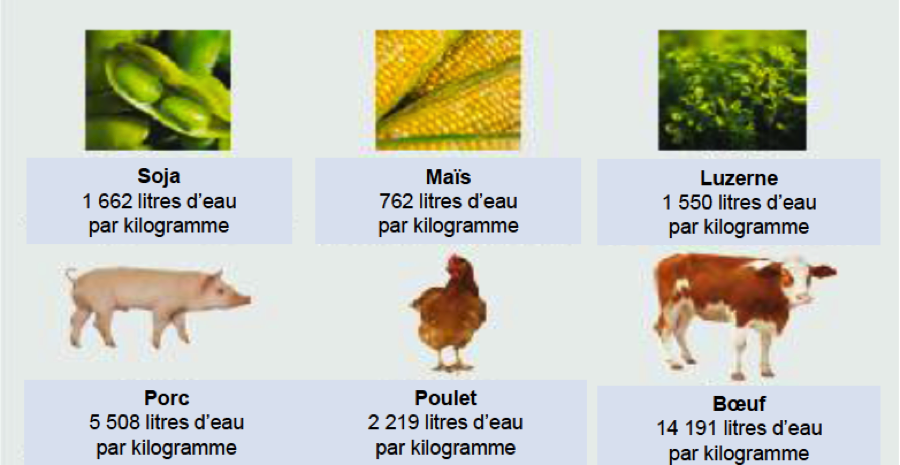
If we combine that idea with another of his charts, below, that shows how much water is currently used in the manufacture of 1KG of production, we get to see how agricultural demand for water is set to skyrocket.


Luzerne is Alfalfa in English.

We can repeat this analysis for many different sectors, and get similar results, from Industry to Energy.

It would be easy to simply dismiss this as an Emerging World problem, to say water shortages will derail the Chinese economic miracle, but we in North America will be unaffected. Unfortunately such isolationist thinking misses the point, and emphasizes the importance of organizations like the Caisse holding conferences like this.

China is currently the world’s largest car market, and a huge source of profits for GM, Ford, et al. GE, Coca Cola, and many other household names have tied their future growth to the growth of these markets. If that growth gets derailed, they get derail; think about the recent hype over whether Apple would introduce a low-end iPhone for the Chinese market.

Many places in Europe, such as the UK and Germany face similar water shortages to China, whilst Belgium is worse than India, according to the World Bank.

North America is no longer immune to disruptions in global food supplies. In recent years we have seen spikes in the overseas price of rice, and wheat translate into higher prices domestically, whilst the underlying prices of meat on the CME continues to rise, see chart below.


Inflation can be a major threat to pension providers like the Caisse over the long-term, as it erodes real returns whilst increases index linked liabilities.

What then is the opportunity? According to McKinsey $57 Trillion needs to be spent on infrastructure, of which $11.7 Trillion alone needs to be spent on water infrastructure, between now and 2030. China expects to spend $850 Billion over the next 10 years on water infrastructure, including a 4-fold increase in desalination facilities.

India currently has about 1/5th the storage capacity of China. Much of the Monsoon water just floods the land then runs off, so there are plenty of opportunities to build storage dams, which could be linked to hydropower as well. India is also building desalination plants. The Minjur desalination plant, at 36.5 million M3 is South East Asia’s largest.

There is also a huge need for improved treatment of wastewater – India treats only a fraction of its used domestic wastewater.

Again, it would be easy to dismiss some of this as yet more infrastructure spending, especially in China, in countries that are economically too dependent on infrastructure spending, but as José Serra showed in Brazil, increasing spending on water treatment can reduce healthcare costs, as fewer children catch and die of gastrointestinal diseases. Remediating wastewater may not return rivers to their former glory, something like 28 000 in China appear to have stopped flowing, but turning rivers like the Tietê and Pinheiros from open sewers to at least livable-with makes citizens lives less unpleasant.

For an organization like the Caisse, these represent a variety of opportunities. Desalination plants can be built and operated under long-term concessions, as can municipal water services. Municipalities may issue infrastructure bonds, backed by utility taxes. The companies that actually construct these plants may list their shares, or raise project finance.

The companies providing these services may be from Quebec, they may be European like Suez, or they may be part of the Emerging Portfolio; one of the first Indian construction companies I ever met had just finished building a new sewer system in the unfashionable part of Saudi where I had lived as a teenager.

I am embarrassed to say, I do not know how long it takes to build a desalination plant, but I would guess 5 years including permitting and land acquisition – possibly less in China, more in India. So what are the chances of a crisis during the life of the project?

India last had a Foreign Exchange crisis in 1991. It has been obvious for a while that a new one is brewing, even if not as bad as ’91, so if India has a major crisis ever 25 years or so, that puts the probability of a crisis during the construction phase at about 20%, and during a typical 25 year concession period 100%.

Brazil had a mini crisis a year or so after the introduction of the Plano Real, as the euphoria wore off. It had a major crisis following the Russian default, then again when it became clear Lula was going to win the Presidency in 2002. If we add the current correction to the list (I think that is pessimistic) we get a minor crisis about every 5 years, so we would get one crisis during the construction period and 5, at least one of which could turn major, during a 25 year concession.

So stepping back, it is clear that taking such a long view of investing makes perfect sense for organizations like the Caisse or CPPIB, even if voters do occasionally complain. I think the many citizens in the US and elsewhere will be soon wishing their Governments had been so forwards thinking.

It is also clear why so many of these firms like the Caisse and the Norwegian Pension Fund take Socially Responsible Investing in all its forms so seriously. Only then can you really quantify the spectrum of risks they face going forwards.


It was a great conference and my compliments to Meggie Daoust and Johanne Pichette for such a great job.